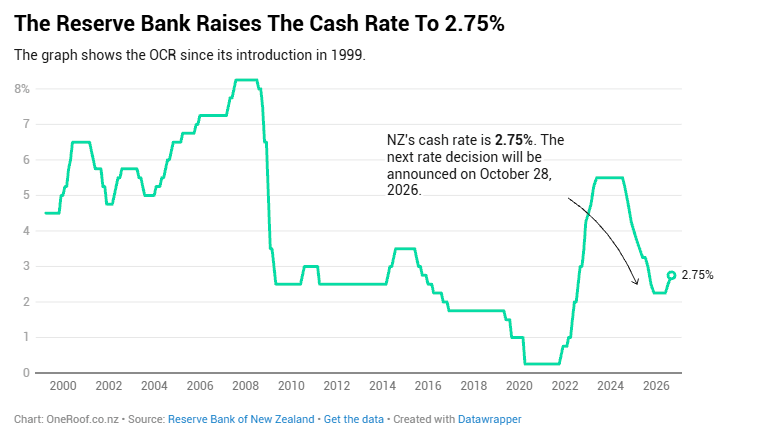
The Reserve Bank of New Zealand (RBNZ) has officially raised the Official Cash Rate (OCR) by 25 basis points to 2.75%. Following a similar hike in July, this marks the second rate increase of 2026 as the Monetary Policy Committee moves to systematically dial back monetary stimulus and steer inflation back toward its 2% target.
For independent economists like Tony Alexander, the move is no surprise. However, for property managers and landlords, this shift changes the operational baseline for the final stretch of 2026 and into 2027.
Here is a breakdown of what this decision means for your portfolio, your tenants, and how you should navigate the shifting property landscape.
1. The Direct Impact on Mortgages: Variable vs. Fixed
The shift in the OCR triggers an immediate ripple effect across bank lending structures, but the type of debt you hold determines how quickly you will feel it:
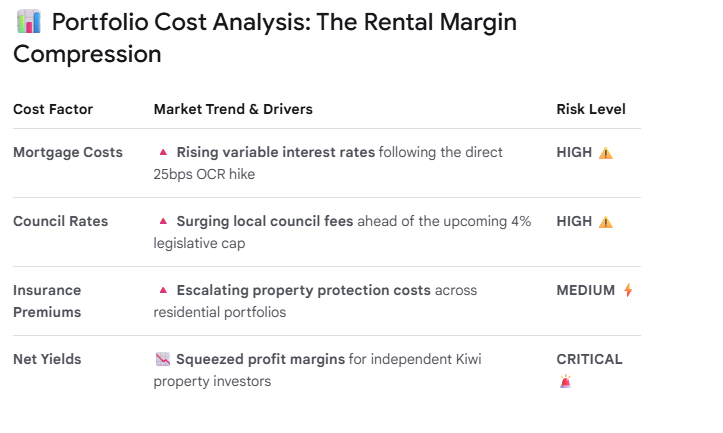
- Floating & Variable Rates: Expect commercial banks to pass this 25-basis-point hike directly on to floating mortgage rates almost immediately. If you or your clients rely heavily on floating lines of credit, debt servicing costs are going up now. [1]
- Fixed Mortgage Rates: The good news is that fixed wholesale borrowing costs had already priced in this particular hike. Because the Reserve Bank’s commentary was slightly less aggressive on core inflation than it was in July, short-term fixed rates face very little immediate upward pressure.
The Strategy: If you have fixed-term mortgages rolling off over the next 6 to 12 months, do not expect rates to drop anytime soon. Economists warn that further increases in fixed borrowing costs are likely as we head into 2027. Sitting down with a financial advisor to secure a stable fixed strategy remains a smart preventative measure.
2. Rent Dynamics and the Coming 4% Council Rates Cap
A major talking point surrounding this economic shift is the ongoing risk of domestic inflation. In particular, landlords are facing substantial pressure from rising municipal costs—chiefly council rates rises as local bodies rush to adjust before a projected 4% legislative cap comes into effect.
Combined with climbing insurance premiums and variable mortgage adjustments, the overall holding costs for investment properties are climbing.
The Strategy: As property managers, it is vital to balance landlord yields with tenant retention. While cost pressures might tempt investors to bump up rents aggressively, real disposable income for households is tightly stretched due to high fuel prices and a softening job market. Drastic rent hikes risk vacancy periods, which are far more costly than absorbing small margin squeezes. Focus on data-driven, incremental rent reviews aligned with exact suburb medians
3. A Flat Housing Market Meets “FOOP”
Tony Alexander’s latest real estate agent survey highlights a distinct psychological shift in the market: FOOP (Fear Of Overpaying).
- Buyer Anxiety: Approximately 42% of agents report that active buyers are explicitly worried about interest rates climbing even higher.
- Falling Investor Presence: Nearly half (49%) of surveyed agents note a decline in investor buyers. A combination of tax policies, lower expectations for immediate capital gains, and high borrowing costs are keeping secondary buyers on the sidelines.
- Flat Prices: Because of this, the residential sales market remains flat, with a net 41% of agents reporting that house prices are holding steady or easing slightly.
The Strategy: If you have clients looking to divest or expand their portfolios, the current market calls for patience. For buyers, the flat pricing structures present excellent opportunities to pick up properties with reduced competition from other investors. For sellers, proper staging, aggressive property marketing, and highly realistic pricing expectations are mandatory to secure a sale
Proactive Steps for Property Managers
- Audit Portfolio Debt Exposure: Reach out to your landlords to discuss their financing health. Help them identify which properties are exposed to floating changes or upcoming fixed-term expirations so they can plan cash flows through 2027.
- Focus heavily on Tenant Retention: With unemployment ticking up nationally and living costs remaining high, finding high-quality, stable tenants is paramount. Prioritize long-term lease renewals with dependable tenants over high-risk, maximum-dollar turnarounds.
- Optimize Maintenance Expenditures: Squeezed margins mean landlords will look to cut costs. Show your value by auditing preventative maintenance schedules to stop minor issues from turning into massive, budget-breaking emergency repairs down the line.
The RBNZ’s next rate decision is scheduled for October 28, 2026. With economists pricing in roughly a 50/50 chance of a third consecutive hike, staying informed and operationally lean is your best defense against shifting macroeconomic tides.
Source from Onerrof: Tony Alexander
Additional commentary from him can be found at https://www.oneroof.co.nz/news/tony-alexander-what-the-latest-ocr-hike-means-for-mortgage-rates-and-house-prices-50146
The opinions and research contained in this article are provided for information purposes only, are intended to be general in nature, and do not take into account your financial situation or goals.